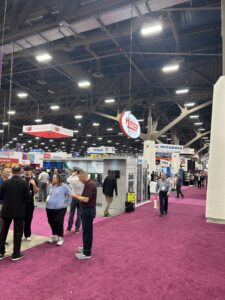
The 2026 NACS Show reinforced something we’ve observed in our research: convenience-store foodservice has significant growth potential, but capturing that growth is becoming increasingly complicated.
Across conversations with Michael Foods, EA Sween, Rich Products, Cargill, CJ Schwan’s, Reser’s and others, a consistent theme emerged. Manufacturers are innovating, retailers are investing, and consumers have more choices than ever. Yet success increasingly depends on matching those investments to the realities of individual stores and customers.
Here are five takeaways from Las Vegas.
1. Not Every Convenience Store Should Have the Same Foodservice Program
One of the most revealing conversations came from Michael Foods, where we discussed differences between East and West Coast convenience-store foodservice.
Many Western operators aspire to become the next Wawa. But replicating that model requires more than adding prepared foods.
Consider two stores operating under the same banner. One serves a neighborhood where security concerns and customer behavior may limit the viability of a full foodservice program. The other has the traffic and customer profile to support a broader menu.
The appropriate solution might be packaged hard-boiled eggs at one location and a comprehensive prepared-food offering at the other.
The consulting implication: Store-level segmentation should precede foodservice investment. A uniform rollout may be easier to manage, but it isn’t necessarily the most profitable strategy.
2. Foodservice Can Change the Competitive Equation
Another Michael Foods observation involved two nearby stores. One offered gasoline at a lower price but lacked foodservice. The other charged more for fuel yet reportedly attracted significantly more traffic.
It’s an anecdote, not a controlled study, but the strategic question is compelling: Can foodservice make a convenience store a destination rather than simply a fuel stop?
The answer likely depends on execution, consistency, and whether the food offering provides a compelling reason to return.
The implication for retailers is that foodservice performance should be evaluated beyond product-level margins, including its potential contribution to overall store traffic and repeat visits.
3. Innovation Must Solve an Operating Problem
At Rich Products, we saw specialty beverage equipment capable of producing multiple customized drinks, potentially bringing offerings associated with chains like Dutch Bros and Swig into convenience retail.
The opportunity is appealing, but so are the operational questions: Where does the equipment fit? Who prepares the beverages? How much labor is required? Can stores maintain consistency during peak periods?
Cargill also emphasized the pace of beverage innovation, alongside continued interest in proteins.
Meanwhile, discussions with CJ Schwan’s highlighted growing customer demand for limited-time offers.
The challenge isn’t generating more innovation. It’s determining which innovations can be executed profitably within existing operating systems.
4. Waste, Shelf Life and Product Quality Are Strategic Variables
EA Sween raised concerns about waste, including estimates in the 20–30% range in certain situations, alongside labor availability and pressure on consumer spending.
Those economics matter enormously when evaluating fresh foodservice expansion.
At Michael Foods, discussions about real versus dehydrated potatoes illustrated another consideration: whether higher-quality products create enough customer or operational value to justify their cost.
Manufacturers and retailers must evaluate the complete economic equation: ingredient costs, preparation requirements, shelf life, waste, labor and repeat purchase.
Lower acquisition cost doesn’t necessarily translate into better operating economics.
5. Growth Requires Better Decisions About Production and Distribution
Our discussion with Reser’s highlighted questions surrounding packaging, portion sizes, refrigerated versus frozen formats, and the economics of serving different types of operators.
These are not simply product-development decisions. They influence capital investment, manufacturing flexibility, distribution economics and market accessibility.
The growing role of commissaries and centralized production adds another dimension. As retailers seek consistency and labor efficiency, manufacturers must understand where food is prepared, who controls purchasing decisions, and how products reach individual stores.
The strategic opportunity may be less about pursuing the largest national accounts and more about identifying regional operators and production partners with attractive economics and accessible decision-makers.
The Bottom Line
NACS 2026 demonstrated that convenience foodservice innovation is alive and well. But innovation alone won’t determine the winners.
The next phase of growth will require more disciplined decisions about which stores to serve, which products to offer, how to execute them, and where manufacturers can create measurable value.
For both retailers and suppliers, the question is shifting from “What can we sell?” to “Where can we win profitably, and why?”
That’s where research, segmentation and sound strategy become competitive advantages.
Get practical foodservice intelligence delivered to your inbox. Our subscribers receive original research, industry analysis, blog updates, and announcements on new studies. Sign up to receive our communications.
Recent Comments